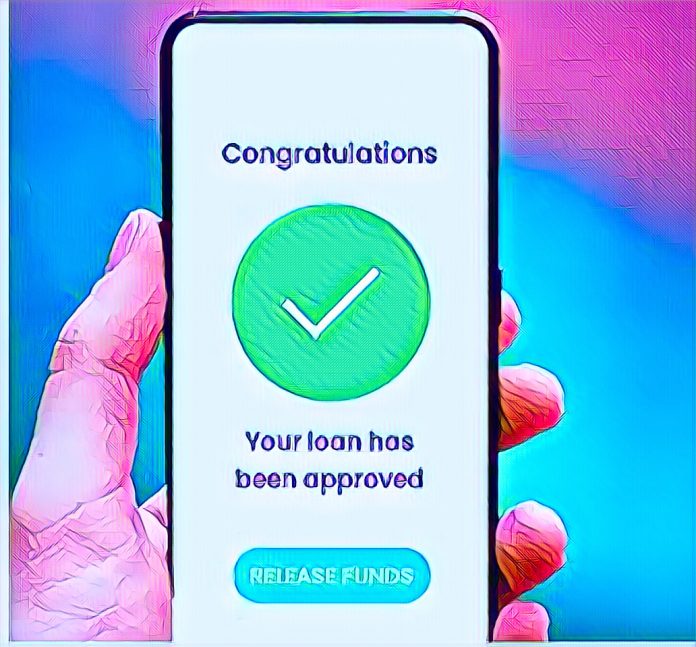
Nigeria is experiencing a significant rise in the number of loan apps, with a 64% surge in Naira-based platforms as more citizens turn to digital solutions to meet their financial needs. This dramatic increase highlights the growing demand for quick and accessible credit in a country where traditional banking services often fall short.
The proliferation of loan apps is driven by the economic challenges facing many Nigerians, including high unemployment rates and a lack of access to conventional credit facilities. These apps offer a convenient alternative, providing instant loans with minimal paperwork and quick approval processes.
Financial technology companies are capitalizing on this demand, rapidly expanding their services to cater to a wide range of borrowers. The ease of access and speed of disbursement make these loan apps particularly attractive to young people and small business owners who need quick cash to manage their operations or personal expenses.
However, this surge also raises concerns about the sustainability and potential risks associated with the rapid growth of digital lending. Experts warn that without proper regulation and consumer protection measures, borrowers could fall into debt traps, struggling to repay high-interest loans and facing aggressive collection practices.
Regulatory bodies in Nigeria are beginning to take notice, with the Central Bank of Nigeria (CBN) exploring ways to ensure that these digital lenders operate within a framework that protects consumers. The goal is to strike a balance between fostering innovation in the financial sector and safeguarding the interests of borrowers.
Despite the challenges, the rise of loan apps has had a positive impact on financial inclusion in Nigeria. Many people who were previously excluded from the formal banking system now have access to credit, enabling them to participate more fully in the economy.
Industry leaders believe that with the right regulatory oversight, digital lending can continue to grow in a way that benefits both lenders and borrowers. By promoting transparency, fair lending practices, and financial literacy, Nigeria can harness the potential of fintech to drive economic development.
As Nigeria navigates this new financial landscape, there is optimism that the digital revolution in lending will lead to more inclusive and equitable economic growth. The continued evolution of loan apps and fintech solutions holds promise for a more connected and financially empowered population.
Source: Business Day