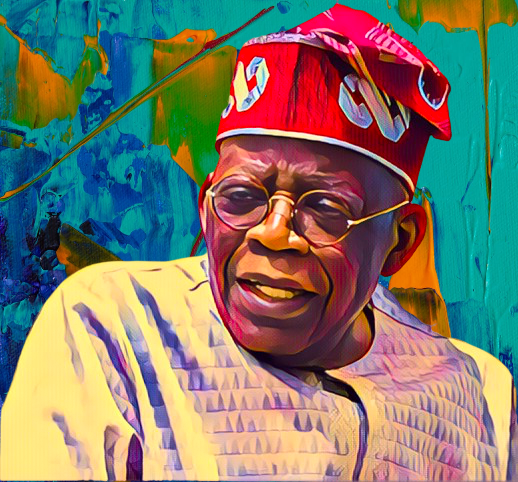
The Nigerian Presidency has sharply countered recent reports from the New York Times concerning the country’s economic condition, asserting that President Bola Tinubu took the helm of a floundering economy on May 29, 2023. Through a statement entitled “Rejoinder to New York Times jaundiced report on Nigeria’s current economic situation,” issued by the Special Adviser to the President on Information and Strategy, Bayo Onanuga, the Presidency delineated the inherited economic challenges and the strategic measures implemented to navigate through them.
A Detailed Rebuttal to Criticism
The statement responded directly to the portrayal in the New York Times, which, according to the Presidency, had unfairly depicted Nigeria’s economic strategies under the new administration. The Presidency critiqued the foreign media’s approach as reductionist and overly pessimistic, failing to recognize the positive strides made amidst economic adversities. It highlighted that the claims of a worsening economic crisis ignored the inherited conditions and the decisive actions taken by Tinubu’s administration, such as the removal of the fuel subsidy and the unification of exchange rates.
The Economic Landscape upon Tinubu’s Ascension
When President Tinubu assumed office, he was met with a plethora of economic issues. The national economy was described as “bleeding,” necessitating immediate and robust policy interventions to prevent further decline. The previous administrations had left the economy in a precarious state, with a national budget that dedicated an overwhelming portion of its revenue to debt servicing, leaving minimal funds for developmental and recurrent expenditures. Furthermore, the longstanding fuel subsidy regime, which had cost the nation approximately $84.39 billion between 2005 and 2022, was no longer sustainable, nor was the artificial maintenance of the Naira’s exchange rate, which had led to significant financial disparities and operational challenges for foreign and domestic businesses.
Progressive Measures and Future Outlook
Amidst the fiscal turmoil, President Tinubu’s administration introduced policies that were crucial for economic stabilization and recovery. The floating of the Naira, despite leading to an initial devaluation, is expected to gradually stabilize, with projections suggesting it could strengthen to between N1000 and N1200 to the US dollar by year’s end.
These economic adjustments have started to bear fruit, evidenced by a trade surplus recorded in the first quarter post-administration takeover and a renewed influx of long-term investors. The presidency also highlighted ongoing efforts in the agricultural sector aimed at curtailing food inflation through enhanced production and state-supported retail outlets offering food items at reduced prices.
The statement from the Presidency also made it clear that Nigeria is not isolated in its economic struggles. Similar challenges are being faced globally, with significant economies like the United States and countries across Europe grappling with rising costs of living. The Nigerian government is actively drawing parallels to these global conditions to contextualize its own struggles and the measures it is taking to mitigate them.
Source: Vanguard